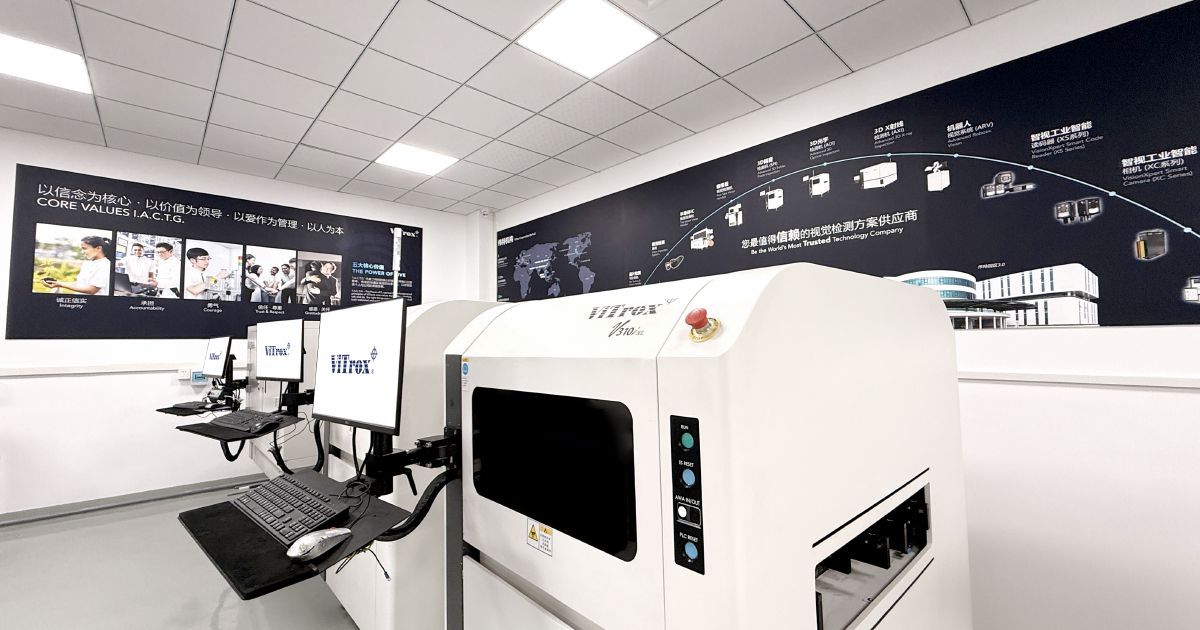

KUALA LUMPUR: Emerging supply constraints and a moderating growth momentum have prompted AmInvestment Bank to downgrade ViTrox Corporation Bhd to “Hold” from “Buy”, despite the company registering 173 per cent surge in core profit in the first nine months.
Despite the strong financial showing, AmInvestment analyst Paul Yap Ee Xing highlighted that growth momentum is expected to moderate as the company faces a high base effect.
The group’s book-to-bill ratio has already eased from 1.5 times in the previous quarter to 1.1 times.
Management has guided fourth-quarter revenue to land between RM403 million and RM459 million. Its automated board inspection (ABI) backlog stands at a healthy RM399 million, offering revenue visibility into the first half of 2027.
A pressing concern for the technology firm lies in emerging supply chain bottlenecks. Following a significant order pull-in during the third quarter, ViTrox had to draw down its inventory to meet near-term demand, leaving a tighter material buffer for upcoming quarters.
“AXI (automated X-ray inspection) equipment output is constrained by the supply of X-ray tubes.
“While the procurement and R&D teams are actively exploring alternative sources across different countries and suppliers, challenges remain in bridging gaps in pricing and technical specifications,” said Yap in a note.
The automated vision inspection solutions provider reported a 9M 2026 core net profit of RM263 million, beating market consensus by coming in at 83 per cent of full-year estimates.
A key catalyst for this robust performance was the deployment of AI infrastructure, which propelled communication-related revenue to 42 per cent of the group’s total.
ViTrox’s QX AXI equipment has been adopted as the standard by a major hyperscaler, single-handedly contributing 15 per cent to the group’s revenue, noted AmInvestment.
Looking forward, potential growth catalysts for ViTrox include advanced packaging and inspection solutions designed for next-generation AI accelerator boards and cold plates.
AmInvestment is keeping its target price for ViTrox unchanged at RM10.25, which is based on a target price-to-earnings (PE) multiple of 40 times on blended 2027/28 earnings per share.
Given the current trajectory, the firm caution that upside surprises will become increasingly difficult for the company to deliver amidst tightening supply hurdles.