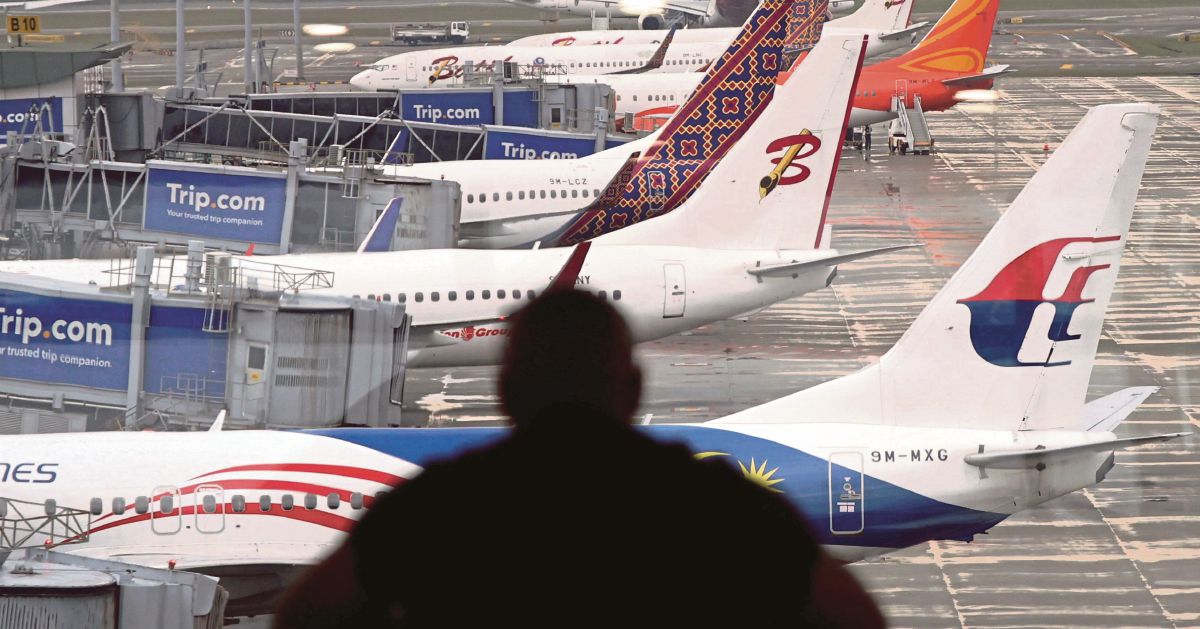

KUALA LUMPUR: Malaysia Aviation Group Bhd (MAG) has made sound progress since its 2021 restructuring, supported by stronger passenger traffic, improved operating performance and sustained positive cash flow.
However, MAG’s financial position remains constrained by high borrowings and negative shareholders’ funds, according to MARC Ratings.
MARC said the group’s improving performance and strategic importance underpin its preliminary ratings of MARC-1IS and AAAIS for its proposed Islamic commercial papers (ICP) and Islamic medium-term notes (IMTN) programmes, with a combined limit of RM1 billion.
The long-term rating carries a stable outlook.
MAG, wholly owned by sovereign wealth fund Khazanah Nasional Bhd, is the parent of national carrier Malaysia Airlines Bhd.
It is the country’s only integrated aviation group, providing passenger airline, air cargo and aviation support services.
MARC said the ratings reflected the group’s strategic importance and the expectation of extraordinary support from Khazanah if required.
Khazanah’s longstanding financial commitment supports this, including an equity injection of about RM500 million in 2025 despite MAG’s return to profitability.
The group’s available seat kilometres rose 15.5 per cent year-on-year to 53.2 billion in 2025, surpassing the pre-pandemic level of 48.7 billion.
Its passenger load factor improved to 81.1 per cent from 80.4 per cent in 2024 and 75 per cent in 2019.
MAG accounted for an estimated 17 per cent of Malaysia’s passenger traffic, with its extensive network, oneworld membership and airline partnerships supporting domestic and international connectivity.
Improved unit costs have sustained profitability, although passenger yields and unit revenue remain under pressure.
Operating cash flow stood at RM970 million in 2025, down from RM1.2 billion in 2024, mainly due to higher aircraft maintenance and redelivery-related payments.
However, fleet renewal will require substantial investment, with cumulative capital expenditure estimated at RM26 billion through 2030, including RM22.3 billion for aircraft acquisitions and related pre-delivery payments.
While operating leases and delivery financing are expected to ease upfront funding requirements, the programme will increase recurring financial commitments.
Total borrowings rose to RM10.9 billion at end-2025 from RM8 billion a year earlier, mainly due to higher lease liabilities following additions to its aircraft and engine fleet.
MARC expects borrowings to remain elevated as fleet renewal progresses, although fuel and maintenance savings from a younger fleet should provide some relief.
MAG’s shareholders’ funds remained negative at RM2.6 billion at end-2025, largely reflecting accumulated losses from previous years.
Nevertheless, the ratings agency noted the improving trajectory of its standalone financial position and sustained positive operating cash flow.